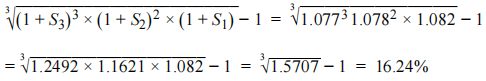

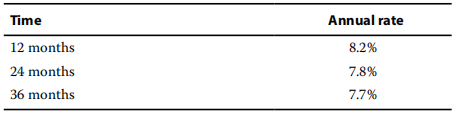
Based on the following observed annual interest rates for government debt of the Republic of South Africa, what is the best estimate of the two-year forward rate one year from today?
A 6.71%
B 7.45%
C 16.24%
解析:
The correct answer is B, 7.45%. To calculate the two-year forward rate one year from today, we use the relationship between the spot rates (current interest rates for specific maturities) and the forward rate. The forward rate is the rate agreed on today for a loan that will begin in the future:
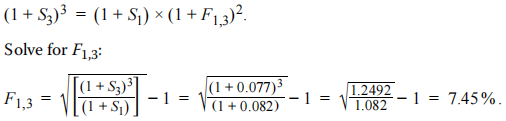
To preclude arbitrage, investing at the three-year interest rate of 7.7%, at the one-year rate of 8.2%, and then at the two-year forward rate one year from today of 7.45% should yield the same result. ZAR100,000 would then grow in three years. ZAR100, 000 × (1 + 0.077)3 = ZAR124, 924 and ZAR100, 000 × (1 + 0.082) × (1 + 0.0745)2 = ZAR108, 200 × 1.0782 = ZAR124, 922 are approximately equal (with the difference due to rounding). Response A is incorrect. It calculates F2,3, or the one-year forward rate in two years, and uses the incorrect interest rate, S1, instead of S2:
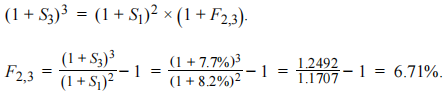
Response C is incorrect. It calculates the geometric average of the three rates: